
Butchers, bakeries and smash burgers: the independents rewriting British foodvenience
As fuel volumes fall and labour costs climb, Britain’s forecourt and convenience retailers are betting on food. Some are signing up the big franchise brands. The boldest are building their own.
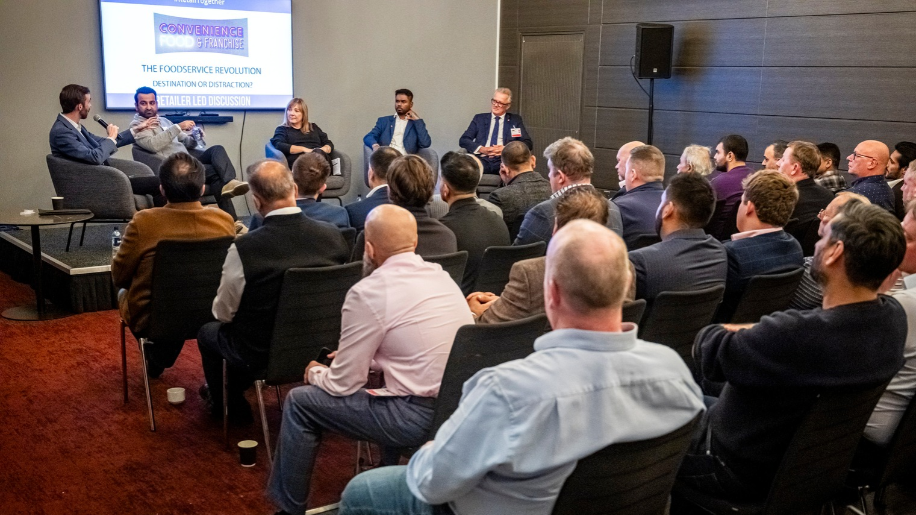
At Retail’s Best Convenience & Franchise, a room full of forecourt owners, convenience retailers and franchisors was asked a simple question: is foodservice a destination or a distraction? For the three retailers on stage, a single-site forecourt in Kent, a 25-store group in Yorkshire and an 84-site national network, the answer is already written into their accounts. Food is no longer an add-on to the shop. It is fast becoming the reason the shop exists. Welcome to foodvenience, where the convenience store and the restaurant meet.
A €29bn reason to stop
The numbers explain the urgency. Lumina Intelligence forecasts the UK food-to-go market will reach €29bn this year, up 3.4% and growing faster than eating out as a whole, with convenience grab-and-go still its largest segment. IGD, which measures the market more broadly, puts it at €32.5bn and expects it to hit €41bn by 2031. The convenience market itself is heading for €57bn, with food-to-go named as one of its biggest growth opportunities.
The pressure is just as real. According to Lumina, 44% of forecourt operators now describe trading as challenging or extremely challenging. Manoj Tandon, director of Park Garage Group, points out that the minimum wage has risen by more than 40% since 2021. Fuel, the industry’s old lifeblood, offers little comfort. “We’re not going to sell more fuel,” says David Charman of Spar Parkfoot. “We’re going to sell less fuel over the next few years.”
The competition has changed too. “It’s anyone who is trying to give your customers food,” says Tandon. That means the coffee shop across the road and the burger chain at the roundabout as much as the forecourt down the street.
Three ways to win
When the global industry looks for foodvenience inspiration, it tends to look to Ireland, Denmark and the US. In the UK, the attention usually goes to London’s avant-garde stores. Yet a great deal of the innovation is coming from independents in the rest of the country, and the three retailers on stage show three very different routes.
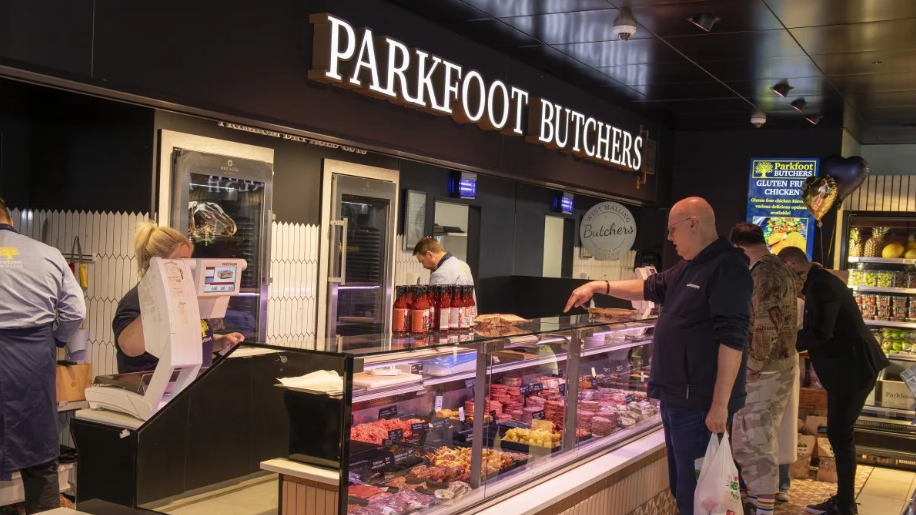
Spar Parkfoot in West Malling has been in the Charman family since 1948. Seventeen years ago, inspired by a convenience store in Northern Ireland that had taken in the village butcher, Charman installed his own butcher’s counter. Today it is the most important part of the shop. COVID turned it into a springboard, as customers rediscovered cooking and never went back. The butchery now produces oven-ready meals, while the kitchen bakes its own sausage rolls and morning goods. Around 40% of what the site sells is Parkfoot’s own brand, and it is now stocked by other stores. “They see us as Parkfoot, supported by BP and Spar,” he says.
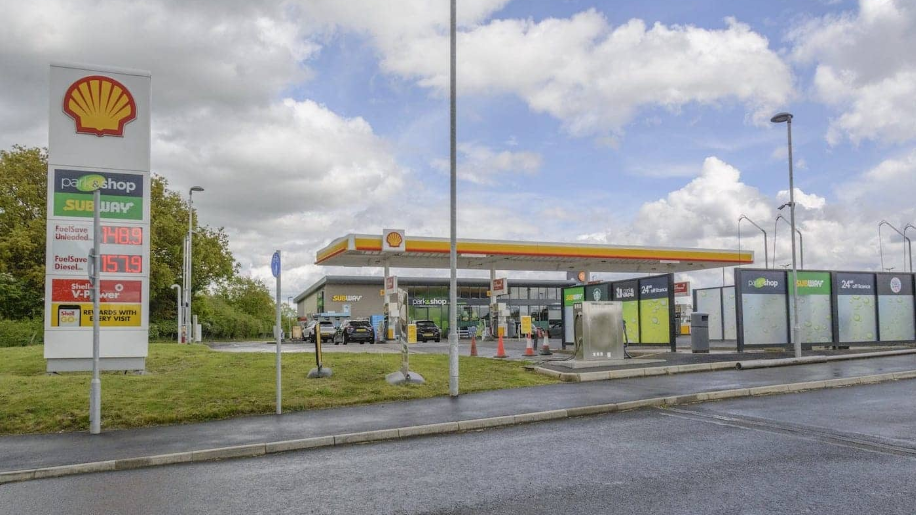
Park Garage Group operates 84 forecourts from Aberdeen to Cornwall under its own Park & Shop fascia, alongside its Park Valet and Park & Vape brands. A 2021 acquisition brought it Subway units and a franchised bakery chain. In April 2024 it replaced the bakery with its own concept, Bakery 79, named after the year the business was founded.
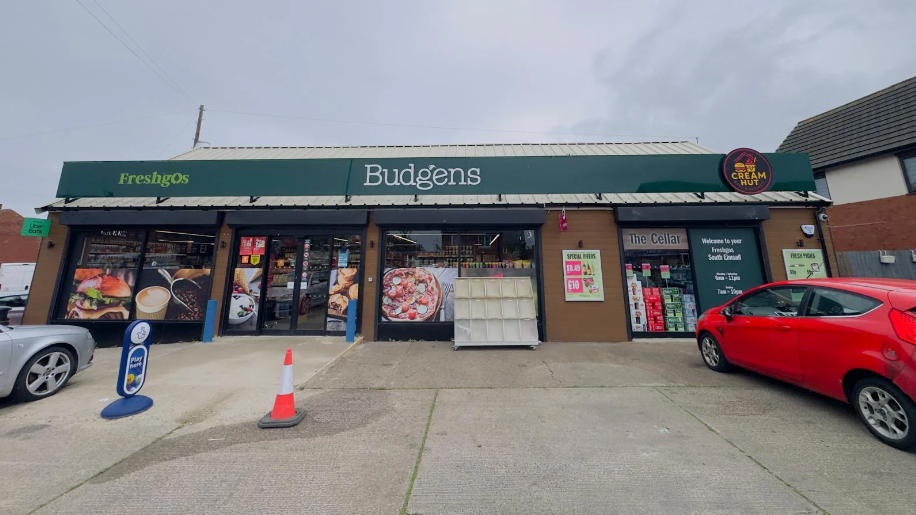
Kopi Kalanathan opened his first store at 19. His FreshGos Group now runs 25 convenience stores across Yorkshire, plus a forecourt and a standalone coffee shop. Eight years ago he started selling desserts. That grew into The Cream Hut, a grill and dessert counter serving smash burgers, rice boxes and milkshakes, followed by the Breaks bakery, Breaks Coffee and the Taddy Coffee Shop. At some sites, families place €115 orders and happily wait half an hour. “The only way to compete is to do something different,” he says.
The hard part
None of this comes easily. “Food service is a lot of effort,” says Tandon. “It’s bloody hard.” Building your own brand, he warns, means writing the health and safety rules, operating manuals and training modules yourself, then making sure every site follows them. “People drive sales,” he says. Where his managers are strong, sales follow.
Consistency is Kalanathan’s biggest headache. A concept that thrives in one store can struggle in the next, which is why he is moving a lot of his logistics and prepping to a distribution center.
Space is another barrier. One independent retailer in the audience pointed out that the average convenience store is just 75 to 95 m², leaving little room for kitchens and extraction. Wenham says more franchisors now offer over-the-counter formats that need neither.
Then there is dinner, the meal the industry has never quite cracked. Charman’s answer is to take the food to the customer. “We’re heading towards delivered hot and cold food,” he says, calling it the only way to keep growing a single site. Tandon is testing pizzas and wondering whether his kitchens could work as dark kitchens after hours. Kalanathan’s Cream Hut already serves the after-work family meal.
What’s next on the menu
The trends are moving quickly. Iced coffee and matcha are surging among Gen Z, and Kalanathan is developing an iced range for Breaks Coffee. Charman is talking to his supplier about matcha too. “It’s not just a fad,” he says. “If we don’t, others will.” Smash burgers have travelled from American diners to Yorkshire convenience stores.
Underneath the menu changes is a deeper shift in attitude. Since COVID, says Charman, customers want premium quality and are happy to pay for it. Kalanathan sees shoppers far more confident buying fresh, hot food from a local store than they were a decade ago. Tandon’s condition is simple: standards. Clean sites and clean toilets come first, or nobody eats.
The franchise world is shifting as well. Wenham sees growth beyond the household names, with regional franchisors expanding outward from local strongholds. Meanwhile, a wave of American chains is arriving in the UK.
Destination, not distraction
So is it worth the effort? Tandon admits it means juggling fuel, valeting, EV charging, vapes and two food brands on a single forecourt, and that the moment one slips, profit slips with it. But handled with the right people, he says, food can be “really, really, really profitable.”
That was the mood at Retail’s Best Convenience & Franchise. Whether retailers sign up a proven franchise, build their own brand or, like Tandon, do both side by side, Britain’s best operators are no longer treating food as a sideline. As Charman put it, after an extraordinary 30 years selling fuel, another journey is just beginning. For many in the room, it is where the money will come from next.